If you trade stocks or options, the wash sale rule is one tax rule you should understand. It can affect when you are allowed to recognize a trading loss, especially if you sell a losing position and quickly return to the same or a substantially identical investment.
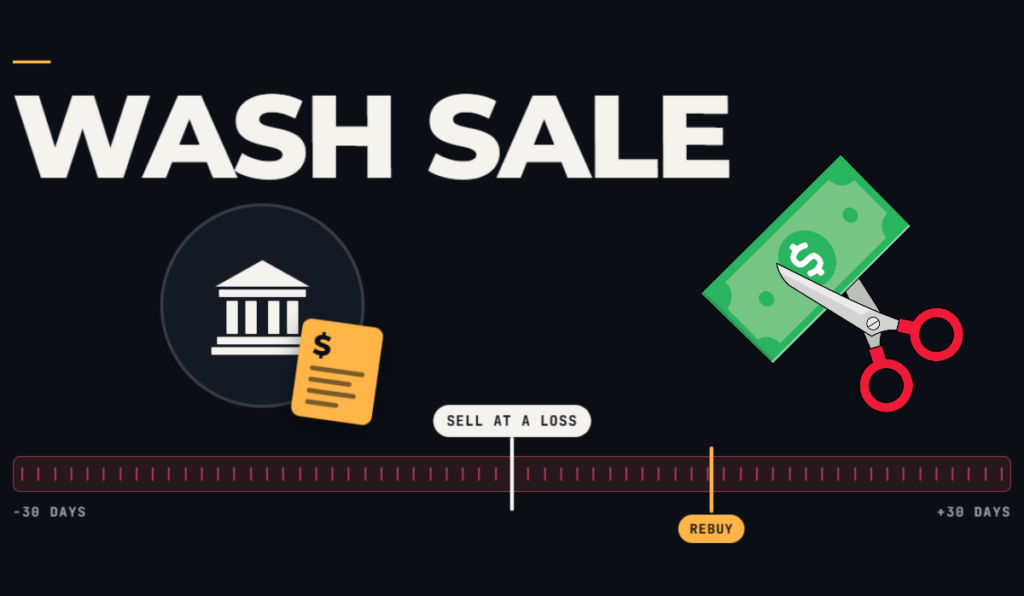
For active traders, wash sales can appear more often than expected because positions are frequently opened, closed, rolled, or adjusted. The good news is that a wash sale does not necessarily mean your loss disappears forever—in many cases, it simply changes when that loss can be recognized for tax purposes.
A wash sale generally occurs when an investor sells a security at a loss and then purchases the same or a substantially identical security within a specific period around that sale. The wash sale rule is designed to prevent investors from selling an investment simply to claim a tax loss and then quickly buying back essentially the same position.
In simple terms, if you sell an investment at a loss and quickly return to nearly the same investment, the loss may not be deductible immediately. Instead, the tax benefit associated with that loss may be postponed until a later transaction.
Imagine you buy 100 shares of a stock at $100 per share and later sell them at $90 per share. That creates a loss of $10 per share, or $1,000 in total, but if you purchase the same or a substantially identical security again within the wash sale period, that loss may not be deductible immediately.
Instead, the disallowed loss is generally added to the cost basis of the replacement investment.
For example:
The loss has not necessarily disappeared. Instead, it has been carried forward into the new position and may affect the taxable gain or loss when that replacement position is eventually sold.
In this video, we explain how the wash sale rule works for active traders, with simple examples involving covered calls and cash-secured puts.
One of the most important details of the wash sale rule is that the 30-day period applies on both sides of the loss-producing sale. It is not enough to look only at what you buy after selling a losing position.
A wash sale may occur if you purchase the same or a substantially identical security:
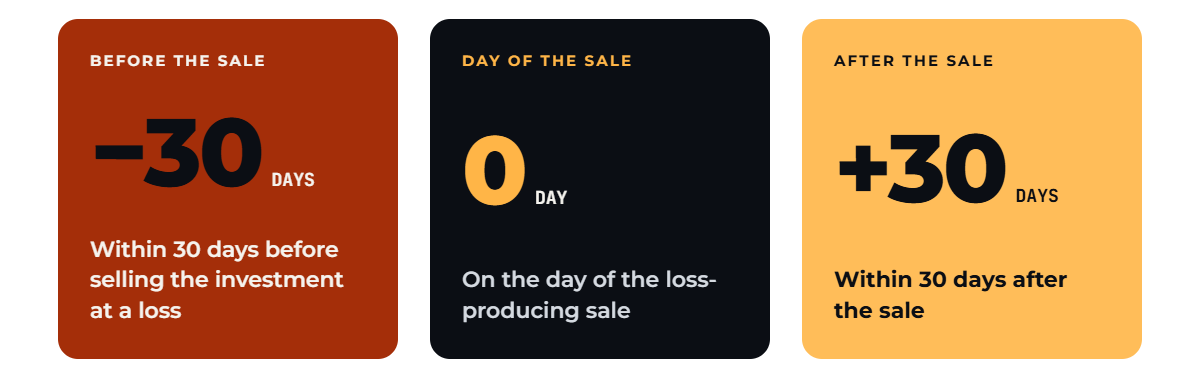
This means traders should not think of the rule simply as “don’t buy it back for 30 days.” Purchases made before the sale can also matter, which is especially important for active traders who regularly enter, exit, adjust, or roll positions.
Waiting more than 30 days before re-entering the same position can sometimes prevent a post-sale wash sale, which is why traders often refer to waiting 31 days. However, waiting this long may not always be realistic for active traders who need to adjust or manage their positions as market conditions change.
Investors generally do not intentionally use wash sales because a wash sale itself does not provide an additional tax advantage. Instead, the behavior that leads to a wash sale is usually connected to an investor’s attempt to realize losses, offset capital gains, or manage their tax exposure.
For example, an investor may own a stock that has declined in value and want to sell it so the loss can offset gains elsewhere in the portfolio. At the same time, the investor may still believe in the stock and want to maintain exposure, creating the temptation to buy it back almost immediately.
Without the wash sale rule, an investor could theoretically:
The wash sale rule is designed to prevent that type of short-term tax maneuver. This is also why the rule is closely associated with tax-loss harvesting, where investors deliberately realize losses but must be careful about how quickly they return to the same or a substantially identical investment.
Wash sales should be considered as part of your broader trading and tax strategy rather than something that must always be avoided. For long-term investors who trade infrequently, wash sales may be relatively easy to manage, but for active traders they can occur much more frequently.
Traders may need to pay closer attention to wash sales when they:
Traders should not let fear of wash sales completely control their trading decisions. If a position needs to be adjusted because it is moving against you, refusing to make that adjustment solely because of a potential wash sale could interfere with the trading strategy itself.
Wash sales can become particularly important near the end of the tax year. If you sell a losing position in December because you want to recognize that loss for the current year but quickly re-enter the same or a substantially identical position, the loss may be deferred rather than providing the tax benefit when you expected it.
This makes timing especially important for traders who are actively managing gains and losses near year-end. Understanding the wash sale rule can help prevent surprises when tax documents are prepared.
Options traders should also understand that changing from one strategy to another does not automatically remove wash-sale concerns. Returning to similar exposure through calls, covered calls, cash-secured puts, or collars on the same underlying stock may still need to be considered.
This is where the idea of a substantially identical security becomes important. Because options can create different types of exposure to the same underlying asset, determining whether a transaction creates a wash sale can be more complicated than simply checking whether the exact same shares were repurchased.
Good recordkeeping is especially important for active traders because frequent transactions can make wash-sale calculations difficult to track manually. Fortunately, modern brokerage platforms and tax software can simplify much of this process by importing transactions and helping calculate tax adjustments.
Traders can now connect brokerage information with tax software and allow transaction data to be processed automatically. This makes managing large numbers of trades significantly easier than it was in the past.
The wash sale rule may sound complicated, but the basic idea is straightforward: if you sell an investment at a loss and then purchase the same or a substantially identical investment within the wash sale period, you may not be able to recognize that loss immediately. The rule exists to prevent investors from claiming a tax loss while quickly returning to essentially the same investment position.
For active stock and options traders, wash sales may simply be part of frequent trading. The goal is not necessarily to fear or avoid every wash sale, but to understand how the rule works, recognize when it may apply, keep accurate records, and consider its tax impact alongside your overall investment strategy.
Subscribe to the Dorian Trader YouTube channel for more practical trading insights, strategy breakdowns, and educational content designed to help you trade with greater knowledge and confidence.
1. Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.